Your Mortgage Payment Isn't Your Housing Budget
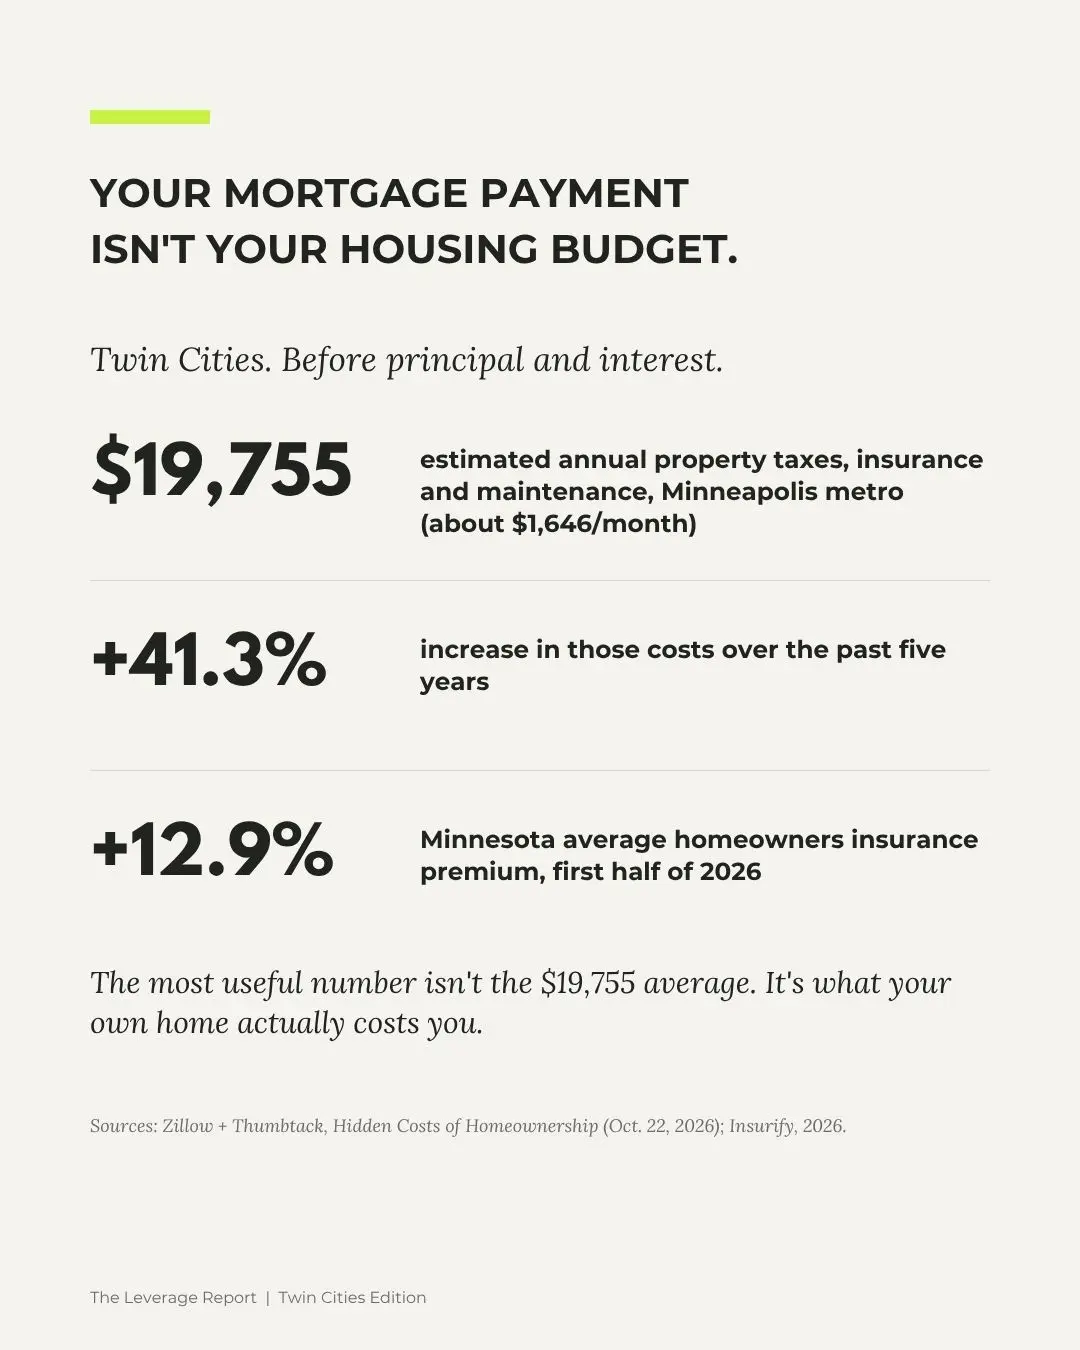
Owning a home in the Twin Cities could cost nearly $20,000 a year before mortgage principal and interest.
That's approximately $1,646 per month.
According to a new Zillow and Thumbtack study, estimated annual property taxes, homeowners insurance, and maintenance in the Minneapolis metro have reached $19,755, up 41.3% over the past five years.
That doesn't mean every homeowner pays that amount. And if your mortgage payment includes taxes and insurance through escrow, you're already covering some of these expenses.
But it raises an important question:
Do you know what your home actually costs you each month?
Here are three expenses worth reviewing and a simple way to evaluate your financial position.
1. Homeowners Insurance: Are You Paying More Than You Need To?
Minnesota homeowners have experienced some significant insurance increases.
According to Insurify, average Minnesota homeowners insurance premiums rose 12.9% during the first half of 2026.
Severe weather, rising repair costs, and replacement expenses are contributing factors.
But here's something interesting:
Research from ICE found that homeowners who switched insurance companies saved an average of 6.6%, while those who stayed with their existing carrier experienced an average 10.4% premium increase.
That doesn't mean switching is always better. Coverage and deductibles matter just as much as price.
Three things worth checking:
· Compare quotes. Get quotes from two or three insurers using the same coverage limits and deductibles.
· Review your roof coverage. Understand whether claims are paid at replacement cost or depreciated actual cash value.
· Ask about discounts. Bundling, protective devices, and certain home improvements may reduce premiums.
The takeaway: Your insurance renewal is an opportunity to review your options, not just another bill to pay.
2. Property Taxes: Is Your Assessment Accurate?
Your property taxes aren't based solely on what your home could sell for.
They're also influenced by local government levies, property classification, and applicable exclusions.
That means your tax bill could increase even if your home's market value stays relatively flat.
Three things worth checking:
· Review your valuation notice. Does the estimated market value reasonably reflect your property's condition and comparable homes?
· Confirm your classification. Make sure your home is correctly classified and you're receiving any eligible homestead benefits.
· Understand your options. If something looks incorrect, contact your county assessor about the review or appeal process.
The takeaway: You may not control local tax rates, but you can make sure the information used to calculate your taxes is accurate.
3. Maintenance: Are You Preparing for the Inevitable?
Unlike a mortgage payment, maintenance expenses don't arrive on a predictable schedule.
Your furnace might run perfectly for years. Your roof could last decades.
But eventually, things need repairs or replacement.
One common budgeting guideline is to set aside approximately 1% of your home's value annually for maintenance.
For a $400,000 home, that's:
· $4,000 per year
· Approximately $333 per month
It's a starting point, not a rule. An older home with aging systems may require more, while a newer property may need less in the short term.
Three things worth checking:
· Know your home's major systems. How old are the roof, furnace, air conditioner, and water heater?
· Plan ahead. Identify repairs or replacements likely within the next three to five years.
· Build a reserve. Set aside money monthly so future repairs don't automatically become financial emergencies.
The takeaway: Maintenance is often predictable over the long term, even when the timing isn't.
What's Your Home Actually Costing You?
Here's a simple exercise worth doing.
Add up your monthly housing expenses:
Expense | Monthly amount |
Mortgage principal and interest | $_____ |
Property taxes | $_____ |
Homeowners insurance | $_____ |
Maintenance reserve | $_____ |
Utilities | $_____ |
HOA dues, if applicable | $_____ |
Your total monthly housing cost | $_____ |
If your mortgage payment includes taxes and insurance through escrow, don't count those expenses twice.
Now ask yourself:
1. Which expenses have increased the most over the past few years?
2. Which expenses could I realistically reduce or better manage?
3. What major repairs or replacements should I be preparing for?
These questions are valuable whether you're planning to move or stay in your home for another twenty years.
What If You're Thinking About Moving?
This is where understanding your complete housing costs becomes especially important.
If you're holding a mortgage rate around 3%, giving it up is a serious financial consideration.
But your mortgage rate doesn't tell the whole story.
A home with an affordable mortgage could still have expensive maintenance needs, rising insurance premiums, or higher-than-expected taxes.
Likewise, moving to a newer home with a higher mortgage rate doesn't automatically mean you'll save money.
The important comparison isn't simply your current mortgage payment versus your next one. It's the total cost of owning each home.
And sometimes, the best decision is to stay exactly where you are.
The Bottom Line
The estimated cost of property taxes, insurance, and maintenance in the Minneapolis metro has increased significantly.
But the most useful number isn't the $19,755 average estimate.
It's what your own home actually costs you.
A little time reviewing your insurance, taxes, and upcoming maintenance could reveal opportunities to save money, avoid surprises, and make better decisions about your future.
Whether you're staying put or considering a move, understanding your numbers gives you more options.
Understand the market. Know your leverage.
The Leverage Report | Twin Cities Edition
Grant Farnum, REALTOR® | Pederson Realty
Sources and Further Reading:
1. Zillow and Thumbtack: Hidden Costs of Homeownership, October 22, 2026
2. Insurify: Home Insurance Rate Trends, 2026
3. ICE Mortgage Monitor: Property Insurance Costs and Savings